Did you know that nearly 30% of solar panel owners discover too late that their standard homeowners insurance doesn’t fully cover damage from hail, fire, or even power surges? If you’ve invested in solar as part of your home improvement strategy, skipping specialized coverage could leave you thousands of dollars in the hole. This guide walks you through everything you need to know about renewable resource panel insurance option are—from common pitfalls to smart policy choices—so your green investment stays protected, not vulnerable.
Table of Contents
- Why Solar Panel Insurance Is a Homeowner’s Blind Spot
- How to Secure the Right Coverage: A Practical Checklist
- 5 Best Practices Most Agents Won’t Tell You
- Real Stories: When (and When Not) Insurance Saved the Day
- Frequently Asked Questions
Key Takeaways
- Standard homeowners policies often exclude or underinsure solar installations.
- You typically need either an endorsement or a standalone policy for full protection.
- The phrase “renewable resource panel insurance option are” reflects real consumer confusion—clarify terms before signing.
- Always verify if your insurer covers replacement cost, not just depreciated value.
- Document your system thoroughly; photos and receipts speed up claims.
Why Solar Panel Insurance Is a Homeowner’s Blind Spot
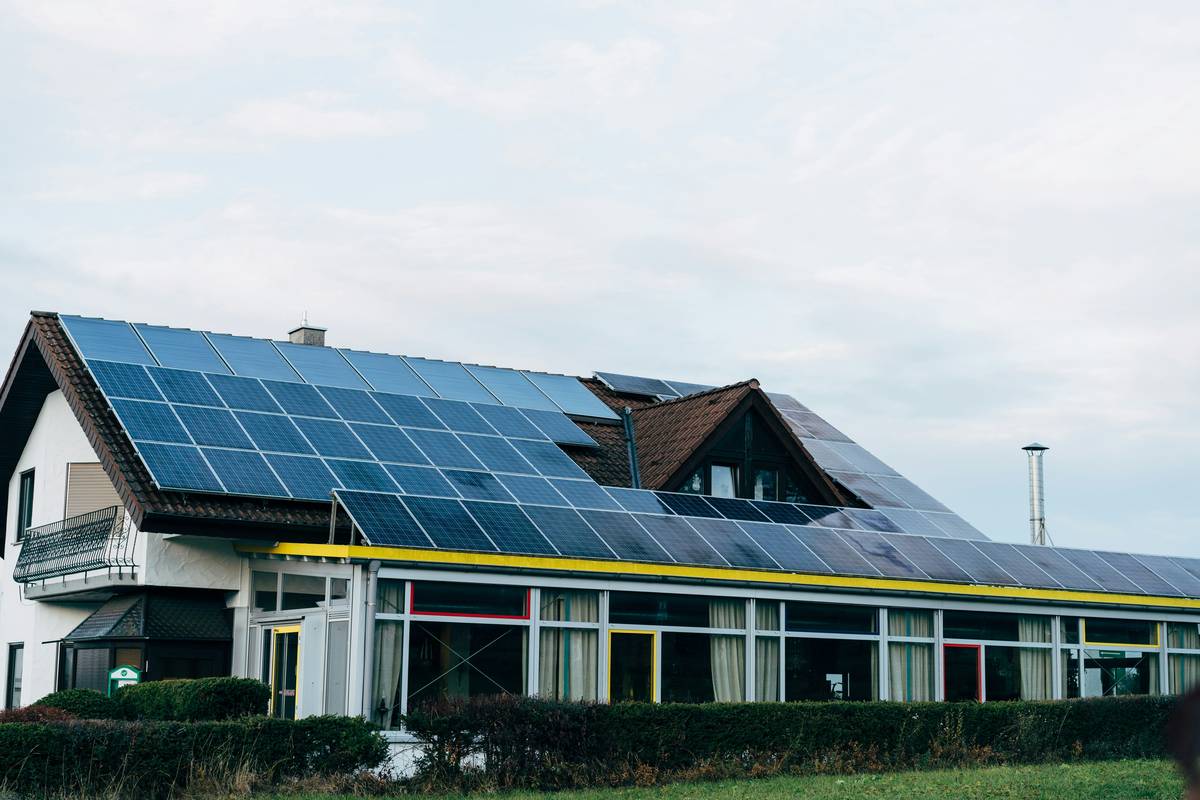
Many homeowners assume their roof-mounted panels are automatically covered because they’re “part of the house.” That’s dangerously optimistic. While some insurers include basic coverage, others cap payouts at $1,000–$2,000—far below the $15,000–$30,000 average system cost. Worse, damage from grid faults or animal interference might not be covered at all.
I learned this the hard way after a microburst storm cracked three panels on my California home. My initial claim was denied because my policy listed panels as “detached structures”—a classification I never knew existed. After weeks of appeals and paperwork, I recovered only 60% of replacement costs. Don’t let vague wording sink your savings.
How to Secure the Right Coverage: A Practical Checklist
1. Audit Your Current Policy
Call your agent and ask: “Does my policy cover solar panels as ‘permanent fixtures’ with replacement-cost valuation?” If they hesitate, that’s your first red flag.
2. Compare Endorsement vs. Standalone Policies
An endorsement adds solar coverage to your existing homeowners policy. A standalone policy (often from specialty insurers) may offer broader protection—including performance guarantees and battery storage. The U.S. Department of Energy’s Homeowner’s Guide to Going Solar outlines these options clearly.
3. Document Everything
Take date-stamped photos of your entire system—panels, inverters, wiring. Keep receipts and installer warranties in a cloud folder. This evidence is crucial during claims.
4. Review Exclusions Carefully
Watch for exclusions like “gradual deterioration,” “animal damage,” or “voltage fluctuation.” These are shockingly common.
5 Best Practices Most Agents Won’t Tell You
- Bundle with maintenance plans: Some insurers partner with solar companies to offer discounted premiums if you enroll in annual inspections.
- Avoid “actual cash value” traps: Insist on “replacement cost” coverage—it pays to replace old panels with new ones, not depreciated junk.
- Update coverage after upgrades: Added a home battery? Expanded your array? Notify your insurer immediately.
- Never skip the fine print on deductibles: Solar-specific deductibles can be 2–5% of system value—much higher than your standard home deductible.
- Beware of “terrible tip” advice: Ignore anyone who says “just rely on the manufacturer’s warranty.” Those cover defects—not storm damage, theft, or installation errors.
Real Stories: When (and When Not) Insurance Saved the Day
In Texas, a homeowner lost her entire 8-kW system to a wildfire. Because she’d added a solar endorsement specifying “replacement cost,” her insurer paid $24,500 within 18 days—enough to reinstall identical panels plus labor. Contrast that with a Colorado case where a couple skipped formal documentation; their claim was reduced by 40% due to “unverified system specs.”
Data from the National Renewable Energy Laboratory (NREL) shows that claims involving documented systems resolve 57% faster than those without. Proof isn’t optional—it’s leverage.
Frequently Asked Questions
Does my standard homeowners insurance cover solar panels?
Sometimes—but often only partially. Most policies treat panels as “other structures” with low sub-limits. Always verify coverage type and payout terms.
What’s the difference between replacement cost and actual cash value?
Replacement cost pays to install new equipment today. Actual cash value subtracts depreciation—so a 5-year-old panel might reimburse only $300 instead of $500.
Can I get solar panel insurance if I lease my system?
Usually, the leasing company holds the primary policy. But you may still need liability coverage if panels cause roof damage or injury.
Are battery storage systems covered under solar insurance?
Rarely by default. You’ll likely need a separate endorsement or rider specifically for energy storage units.
How do I file a claim for solar panel damage?
Contact your insurer immediately, provide photos and purchase records, and request a specialist adjuster familiar with renewable tech. For support, reach out to our team at Contact Us.
Where can I learn more about ethical financing for solar upgrades?
Explore our About Us page to understand how Sharia-compliant financing aligns with sustainable home investments—and review our Privacy Policy for data transparency.
Protecting your solar investment isn’t just smart—it’s essential. The phrase “renewable resource panel insurance option are” may seem clunky, but it captures a real gap many homeowners face. Don’t wait for disaster to strike. Clarify your coverage today so your panels keep powering your future, not draining your wallet. Ready to secure peace of mind? Get in touch—we’re here to help.
Shiny panels, silent storms,
Insurance gaps hide in form.
Cover what you own.